
Corporate Income Tax Rates by U.S. State: 2026 Ranking
Which U.S. states have the highest corporate income tax rates in 2026?
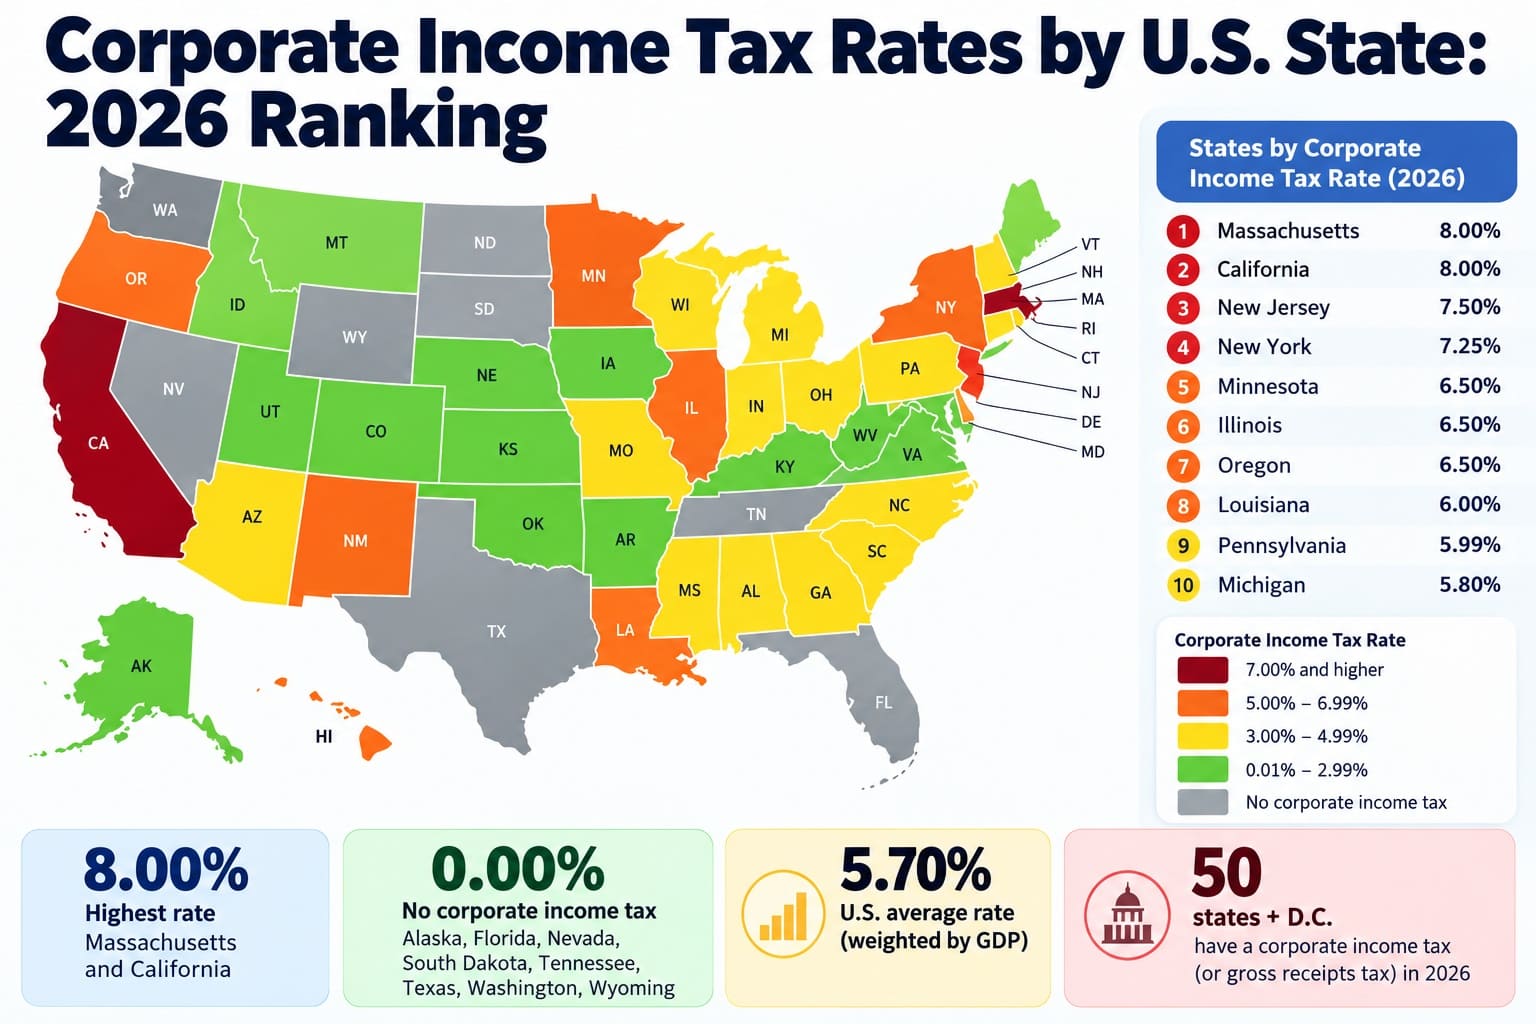
New Jersey leads the 2026 state corporate income tax ranking at 11.50%, followed by Minnesota (9.80%) and Illinois (9.50%). North Carolina has the lowest published top rate among states imposing this tax, at 2.00%. These are statutory top rates, not effective tax burdens.
Metric: highest generally applicable state corporate income tax rate. Unit: percent of taxable corporate income. Direction: highest to lowest. 2026 coverage: all 50 states classified; 44 states with numeric corporate income tax rates ranked, and six states without this tax identified separately. Washington, D.C., is excluded. Data status: 5 official_value; 39 industry_observed_value; no projections. Sources checked: October 27, 2026.
The table is a compiled research dataset based on 6 independent publishing organizations supplying the 2026 ranked rates, with row-level source and method notes shown in the ranking table. Separate official 2025 government publications substantiate historical comparisons; they are not extra ranking observations. Census regional definitions and other validation sources do not supply ranked values.
New Jersey; applies to qualifying corporate taxpayers above its $10 million threshold.
North Carolina; the six no-CIT states are not assigned artificial zero rates.
44 ranked; six states without a corporate income tax. Five directly official values, 39 research-published values.
Calculated from 44 state rates; median 6.50%; D.C. and no-CIT states excluded.
Overview: corporate profits taxes are not business tax burdens
The table compares the top general corporate income tax rate in states that levy a tax on corporate profits. It is not a ranking of every business tax. Federal corporate income tax, local levies, franchise or capital-stock taxes, gross receipts taxes, credits, minimum taxes, industry-specific rules and the location of taxable income can change what a business actually pays.
Six states have no state corporate income tax: Nevada, Ohio, Texas and Washington levy statewide gross receipts-type business taxes instead; South Dakota and Wyoming levy neither a state corporate income tax nor a statewide gross receipts tax. These six states are classified but not ranked at 0%, because no statutory corporate income tax rate exists for them.
Across the 44 corporate-income-tax states, 13 use graduated or conditional top-rate structures and 31 use flat-rate structures in the source comparison. The 2026 ranking keeps top rates even when they apply only to large taxable-income bases. For example, New Jersey's 11.50% figure combines a 9% Corporation Business Tax and a 2.5% Corporate Transit Fee for taxpayers whose taxable income exceeds $10 million; the fee is imposed on the full qualifying taxable income base.
Top 10 states by highest corporate income tax rate
The top three are New Jersey (11.50%), Minnesota (9.80%) and Illinois (9.50%). Connecticut and Maryland tie at rank 9 with 8.25%. The rankings use source-published top rates, not implied rates for a hypothetical company.
2026 highest state corporate income tax rates; percent; competition ranking with ties
| Rank | State | Top rate | Source / method |
|---|---|---|---|
| 1 | New Jersey | 11.50% | Northeast; industry_observed_value; Tax Foundation; 2026; Graduated; 9% CBT plus 2.5% Corporate Transit Fee when taxable income exceeds $10m; applies to entire income base. |
| 2 | Minnesota | 9.80% | Midwest; industry_observed_value; Tax Foundation; 2026; Flat corporate rate. |
| 3 | Illinois | 9.50% | Midwest; industry_observed_value; Tax Foundation; 2026; 7% income tax plus 2.5% personal property replacement tax; combined 9.5%. |
| 4 | Alaska | 9.40% | West; industry_observed_value; Tax Foundation; 2026; Graduated; highest bracket above $222,000. |
| 5 | Maine | 8.93% | Northeast; industry_observed_value; Tax Foundation; 2026; Graduated; highest bracket above $3.5m. |
| 6 | California | 8.84% | West; industry_observed_value; Tax Foundation; 2026; Flat general corporate rate; special entities may differ. |
| 7 | Delaware | 8.70% | South; industry_observed_value; Tax Foundation; 2026; Flat; separate gross receipts tax also applies. |
| 8 | Vermont | 8.50% | Northeast; industry_observed_value; Tax Foundation; 2026; Graduated; highest bracket above $25,000. |
| 9 | Connecticut | 8.25% | Northeast; industry_observed_value; Tax Foundation; 2026; 7.5% base plus 10% surtax on tax liability for qualifying businesses; combined 8.25%. |
| 9 | Maryland | 8.25% | South; industry_observed_value; Tax Foundation; 2026; Flat general corporate rate. |
Top ten includes both states tied at ninth. Some rates include qualifying surcharges; refer to row notes and Methodology.
Chart: the 20 highest state corporate income tax rates
Each bar uses the same 2026 top rate as the ranking. Bar width equals the state rate divided by 11.50%, with New Jersey set to 100% chart length. The chart compares published statutory rates, not dollars collected or effective tax rates.
New Jersey stands 1.70 percentage points above Minnesota; Montana is twentieth at 6.75%. Rates and percentages in the chart are taken from the same 44-state table.
Methodology and source reconciliation
Scope and rank
One observation per U.S. state with a published 2026 corporate income tax rate; 44 numeric observations. Sort descending by raw top rate. Tied rates share a competition rank. Six no-CIT states and Washington, D.C. (8.25%) are excluded from the numeric ranking.
Year and retrieval date
Reference period is tax year 2026, not a forecast. The cross-state table was published in 2026; Georgia's May 2026 update and Utah's March 2026 legislation apply to tax years beginning January 1, 2026. All cited sources were checked October 27, 2026; a future conditional change is not substituted for the confirmed 2026 rate.
Source hierarchy and statuses
Numeric publishers: Tax Foundation for 39 rates; Georgia, North Carolina and Pennsylvania revenue departments, Nebraska Legislature, and Utah Legislature for five directly published statutory rates. official_value means a rate confirmed in state government material; industry_observed_value means the Tax Foundation published the rate. No modeled_projection, calculated_value, or forecast values are used in the 44 ranking rows.
Exceptional rate construction
New Jersey: 9% CBT + 2.5% fee = 11.50% for qualifying taxpayers; Connecticut: 7.5% base x 1.10 surtax = 8.25%; Illinois: 7% corporate tax + 2.5% replacement tax = 9.50%. These published combined top rates are not StatRanker projections.
Derived statistics, not source-published figures: arithmetic mean = sum of the 44 top rates (287.16 percentage points) / 44 = 6.52636%, shown as 6.53%. Median = average of the 22nd and 23rd values in ordered data (both 6.50%) = 6.50%. The 5%-or-lower group contains 14 / 44 = 31.8%. Northeast share of the Top 20 = 9 / 20 = 45.0%. The New Jersey-North Carolina spread = 11.50 - 2.00 = 9.50 percentage points. These are calculations from observed rates, not official forecasts or projections.
Conflicts and adjustments: Tax Foundation's April 2026 comparison lists Georgia at 5.19% and Utah at 4.50%. Later state evidence establishes Georgia at 4.99% and Utah at 4.45% for tax year 2026. These are differences of 0.20 and 0.05 percentage points, respectively; official rates take priority and are never averaged. North Carolina 2.00%, Nebraska 4.55% and Pennsylvania 7.49% were independently checked against government publications. The New York State tax department's northeastern comparison was used to validate relevant high-rate entries, not to add extra observations or count the same organization twice.
Historical changes: inputs and formula. For each state, change in percentage points = 2026 statutory top rate minus 2025 statutory top rate, using the same state and nominal percent unit in both years. Inputs (2025, 2026): Georgia (5.19%, 4.99%; Georgia Department of Revenue), Utah (4.50%, 4.45%; Utah State Tax Commission and Utah Legislature), Nebraska (5.20%, 4.55%; Nebraska Legislature), North Carolina (2.25%, 2.00%; North Carolina Department of Revenue), and Pennsylvania (7.99%, 7.49%; Pennsylvania Department of Revenue). Georgia and Utah historical publications are listed separately in Sources. These 2025 inputs are used only for historical comparisons; the ranking and its average use only 2026 values.
Difference from the publisher's reported mean: Tax Foundation describes the average top rate as approximately 6.57% among states with a corporate income tax. That published estimate does not reproduce the 6.53% mean calculated directly from the 44 confirmed state rates on this page. The publisher's exact averaging inputs are not established here, so no explanation involving the District of Columbia or another unverified denominator is asserted. StatRanker uses the independently reproducible 287.16 / 44 = 6.53% figure throughout.
Geography and exclusions: regions follow the U.S. Census Bureau Northeast, Midwest, South and West definitions. D.C. is a district, not one of the 50 states, so its 8.25% top rate does not enter state statistics. The six states without corporate income tax are not coded as numeric zero rates. The table excludes special financial-institution rates, sector-specific tax rules, non-general alternative minimum taxes, federal taxation and local taxes; Colorado's 4.40% rate carried a potential conditional midyear reduction in the source, not a confirmed replacement used here.
Rounding and meaning: each rate is shown to two decimal places, with source thresholds summarized in row notes. Top marginal rates are neither average statutory rates across all profit levels nor effective rates paid after deductions and credits. Even identical top percentages can correspond to materially different tax liabilities because of thresholds, base definitions and apportionment.
Full 2026 ranking: 44 states with corporate income tax
Search by state or method note, filter by Census region or value status, change the display order, or show the highest 10 or 20. Rank numbers always reflect the original descending-rate ranking. All 44 rows remain visible if JavaScript is disabled.
Top statutory state corporate income tax rate, 2026; percent of taxable corporate income
| Rank | State | Top rate | Source / method note |
|---|---|---|---|
| 1 | New Jersey | 11.50% | Northeast; industry_observed_value; Tax Foundation; 2026; Graduated; 9% CBT plus 2.5% Corporate Transit Fee when taxable income exceeds $10m; applies to entire income base. |
| 2 | Minnesota | 9.80% | Midwest; industry_observed_value; Tax Foundation; 2026; Flat corporate rate. |
| 3 | Illinois | 9.50% | Midwest; industry_observed_value; Tax Foundation; 2026; 7% income tax plus 2.5% personal property replacement tax; combined 9.5%. |
| 4 | Alaska | 9.40% | West; industry_observed_value; Tax Foundation; 2026; Graduated; highest bracket above $222,000. |
| 5 | Maine | 8.93% | Northeast; industry_observed_value; Tax Foundation; 2026; Graduated; highest bracket above $3.5m. |
| 6 | California | 8.84% | West; industry_observed_value; Tax Foundation; 2026; Flat general corporate rate; special entities may differ. |
| 7 | Delaware | 8.70% | South; industry_observed_value; Tax Foundation; 2026; Flat; separate gross receipts tax also applies. |
| 8 | Vermont | 8.50% | Northeast; industry_observed_value; Tax Foundation; 2026; Graduated; highest bracket above $25,000. |
| 9 | Connecticut | 8.25% | Northeast; industry_observed_value; Tax Foundation; 2026; 7.5% base plus 10% surtax on tax liability for qualifying businesses; combined 8.25%. |
| 9 | Maryland | 8.25% | South; industry_observed_value; Tax Foundation; 2026; Flat general corporate rate. |
| 11 | Massachusetts | 8.00% | Northeast; industry_observed_value; Tax Foundation; 2026; Flat general corporate rate. |
| 12 | Wisconsin | 7.90% | Midwest; industry_observed_value; Tax Foundation; 2026; Flat general corporate rate. |
| 13 | Oregon | 7.60% | West; industry_observed_value; Tax Foundation; 2026; Graduated; top bracket above $1m; separate gross receipts tax also applies. |
| 14 | New Hampshire | 7.50% | Northeast; industry_observed_value; Tax Foundation; 2026; Flat business profits tax. |
| 15 | Pennsylvania | 7.49% | Northeast; official_value; Pennsylvania Department of Revenue; 2026; Flat; 7.49% for 2026, down from 7.99% in 2025. |
| 16 | New York | 7.25% | Northeast; industry_observed_value; Tax Foundation; 2026; Graduated; higher rate applies for qualifying taxpayers above $5m. |
| 17 | Iowa | 7.10% | Midwest; industry_observed_value; Tax Foundation; 2026; Graduated; highest bracket above $100,000. |
| 18 | Kansas | 7.00% | Midwest; industry_observed_value; Tax Foundation; 2026; 4% basic rate plus 3% surtax on income above $50,000; top 7%, excluding unrelated business tax credits. |
| 18 | Rhode Island | 7.00% | Northeast; industry_observed_value; Tax Foundation; 2026; Flat general corporate rate. |
| 20 | Montana | 6.75% | West; industry_observed_value; Tax Foundation; 2026; Flat general corporate rate. |
| 21 | Alabama | 6.50% | South; industry_observed_value; Tax Foundation; 2026; Flat; federal corporate tax deduction may apply. |
| 21 | Tennessee | 6.50% | South; industry_observed_value; Tax Foundation; 2026; 6.50% excise tax on net earnings; separate net-worth franchise tax is excluded. |
| 21 | West Virginia | 6.50% | South; industry_observed_value; Tax Foundation; 2026; Flat general corporate rate; local gross receipts levies may apply. |
| 24 | Hawaii | 6.40% | West; industry_observed_value; Tax Foundation; 2026; Graduated; highest bracket above $100,000. |
| 25 | Michigan | 6.00% | Midwest; industry_observed_value; Tax Foundation; 2026; Flat general corporate rate. |
| 25 | Virginia | 6.00% | South; industry_observed_value; Tax Foundation; 2026; Flat general corporate rate; some localities levy gross receipts tax. |
| 27 | New Mexico | 5.90% | West; industry_observed_value; Tax Foundation; 2026; Flat general corporate rate. |
| 28 | Florida | 5.50% | South; industry_observed_value; Tax Foundation; 2026; Flat corporate rate; taxable income exemption affects liability. |
| 28 | Louisiana | 5.50% | South; industry_observed_value; Tax Foundation; 2026; Flat general corporate rate. |
| 30 | Idaho | 5.30% | West; industry_observed_value; Tax Foundation; 2026; Flat general corporate rate. |
| 31 | Kentucky | 5.00% | South; industry_observed_value; Tax Foundation; 2026; Flat general corporate rate. |
| 31 | Mississippi | 5.00% | South; industry_observed_value; Tax Foundation; 2026; Graduated; highest bracket above $10,000. |
| 31 | South Carolina | 5.00% | South; industry_observed_value; Tax Foundation; 2026; Flat general corporate rate. |
| 34 | Georgia | 4.99% | South; official_value; Georgia Department of Revenue; 2026; Flat; current 2026 rate 4.99%; supersedes Tax Foundation 5.19% entry. |
| 35 | Arizona | 4.90% | West; industry_observed_value; Tax Foundation; 2026; Flat general corporate rate. |
| 35 | Indiana | 4.90% | Midwest; industry_observed_value; Tax Foundation; 2026; Flat general corporate rate. |
| 37 | Nebraska | 4.55% | Midwest; official_value; Nebraska Legislature; 2026; Flat; 2026 statutory rate 4.55%, down from 5.20% in 2025. |
| 38 | Utah | 4.45% | West; official_value; Utah Legislature S.B. 60; 2026; flat 4.45% effective for tax years beginning on or after Jan. 1, 2026 (retrospective operation; law effective May 6, 2026). |
| 39 | Colorado | 4.40% | West; industry_observed_value; Tax Foundation; 2026; Flat 4.40% in reference; contingent midyear reduction was noted. |
| 40 | North Dakota | 4.31% | Midwest; industry_observed_value; Tax Foundation; 2026; Graduated; top bracket above $50,000. |
| 41 | Arkansas | 4.30% | South; industry_observed_value; Tax Foundation; 2026; Graduated; highest bracket above $11,000. |
| 42 | Missouri | 4.00% | Midwest; industry_observed_value; Tax Foundation; 2026; Flat general corporate rate; federal income tax deduction rules apply. |
| 42 | Oklahoma | 4.00% | South; industry_observed_value; Tax Foundation; 2026; Flat general corporate rate. |
| 44 | North Carolina | 2.00% | South; official_value; North Carolina Department of Revenue; 2026; Flat; 2.00% for tax year 2026, down from 2.25% in 2025. |
No states match the selected filters.
The published rate is conditional in some states. Source names and status appear in every row; absolute source URLs are grouped in Sources. D.C. and the six no-CIT states are excluded from rate ranking and derived statistics.
Four findings from the reconciled 2026 ranking
Key Insight
The top-rate range is 9.50 percentage points: New Jersey at rank 1 (11.50%) minus North Carolina at rank 44 (2.00%). The 44-state median is 6.50%, compared with a mean of 6.53%.
Notable Pattern
14 of 44 states (31.8%) have a top rate of 5.00% or lower. That count includes Georgia at its government-confirmed 4.99%; using the older 5.19% value would leave 13.
Regional Concentration
All nine Northeast states appear in the Top 20. They account for 9 of 20 entries (45.0%), using the Census four-region classification.
Outlier: Georgia source discrepancy
Georgia ranks 34th at 4.99% using its revenue department's 2026 rate. The earlier 5.19% industry table is 0.20 percentage points higher; that discrepancy is resolved by official-source priority, not averaged.
What the 2026 state corporate tax ranking means
A top statutory rate describes the upper end of a state's general corporate income tax schedule. It is useful for identifying statutory differences and the thresholds that may matter to a profitable C corporation, but it does not predict an individual company's tax bill. A company with taxable income below a top bracket may face a lower rate, while credits, deductions and multistate income allocation can change the final liability.
The top ranks should not be read as a universal list of the most costly states for business. New Jersey's 11.50% depends on a qualifying income threshold; Connecticut's 8.25% depends on surcharge eligibility; and states without a corporate income tax can still impose gross receipts taxes or other charges. For planning, compare the complete tax base, nexus and apportionment rules alongside the stated rate.
Effective years matter: Arkansas remains at 4.30% in this 2026 ranking, while its enacted 4.10% top rate begins in tax year 2027. The Tax Foundation table also flagged a possible conditional change to Colorado's 4.40% 2026 rate. Neither future-year nor unconfirmed conditional values are substituted into this table.
FAQ: 2026 state corporate income taxes
Which state has the highest corporate income tax rate in 2026?
New Jersey is first at 11.50%. This is a qualifying top rate composed of a 9% Corporation Business Tax and a 2.5% Corporate Transit Fee for taxable income above $10 million; it is not the standard rate paid by every corporation.
Which state has the lowest corporate income tax rate among taxing states?
North Carolina ranks 44th at 2.00% for tax year 2026, as published by the North Carolina Department of Revenue. That is lower than the 2.25% rate in 2025.
Why does the ranking contain 44 states rather than 50?
Six states do not levy a state corporate income tax: Nevada, Ohio, South Dakota, Texas, Washington and Wyoming. Four of them impose gross receipts-type taxes. No fictitious 0% corporate income tax rate is assigned to these jurisdictions.
Why is Georgia listed at 4.99% rather than 5.19%?
The Georgia Department of Revenue publishes 4.99% following legislation enacted in May 2026 and applicable to tax years beginning January 1, 2026. The earlier Tax Foundation 2026 rate table still shows 5.19%; this ranking uses the later official value.
Why is the 2026 Utah corporate tax rate 4.45% rather than 4.50%?
Utah S.B. 60 was signed March 23, 2026. It reduced the corporate franchise and income tax from 4.50% to 4.45%, with retrospective operation for tax years beginning on or after January 1, 2026. Its general effective date was May 6, 2026. The earlier Tax Foundation table predates the change.
Are all values official government-published tax rates?
No. Five rows use direct official state publications and are marked official_value. Thirty-nine rows use published Tax Foundation tax-rate observations and are marked industry_observed_value. Each numeric row shows its status and publisher.
Are these forecast corporate tax rates or 2026 observed collections?
Neither. These are tax-year-2026 statutory rate schedules and qualifying top rates. They are not forecasts, collections, effective tax burdens or model-based corporate tax projections. Mean, median and counts on the page are separately calculated from the 44 confirmed rates.
Does the calculation include federal tax or the District of Columbia?
No. This ranks only the general state corporate income tax component of the 50 states. Washington, D.C. has a published 8.25% rate, but is excluded because it is not a state. Federal corporate income tax is not added.
Does a 7% top rate mean every dollar of corporate income is taxed at 7%?
Not necessarily. Graduated brackets, surtaxes, exemptions and thresholds determine how the rate applies. For example, New Jersey's top figure involves a $10 million taxable-income threshold; Illinois' 9.50% includes two corporate taxes. See each row's method note.
Sources and their roles
Tax Foundation - State Corporate Income Tax Rates, 2026
numeric_source / 39 ranked rows; classification for six no-CIT statesPublished state-by-state 2026 tax brackets and special-rate notes. One research publisher, not counted as multiple independent sources because it cites several underlying laws.
https://taxfoundation.org/data/all/state/state-corporate-income-tax-rates-brackets/Georgia Department of Revenue - Corporate Income and Net Worth Tax
numeric_source / official_valueCurrent government rate of 4.99%, used instead of the earlier 5.19% in the research table.
https://dor.georgia.gov/taxes/corporate-income-and-net-worth-taxNorth Carolina Department of Revenue - Corporate Tax Rates
numeric_source / official_valueTax-year table confirming 2.00% for 2026 and 2.25% for 2025.
https://www.ncdor.gov/taxes-forms/corporate-income-franchise-tax/corporate-income-and-franchise-tax-ratesPennsylvania Department of Revenue - Corporation Tax Rates
numeric_source / official_valueCorporate net income tax rates confirming 7.49% for 2026 and 7.99% for 2025.
https://www.pa.gov/agencies/revenue/resources/tax-rates/corporation-tax-ratesNebraska Legislature - Revised Statute 77-2734.02
numeric_source / official_valueStatutory corporate rate of 4.55% for 2026, with the preceding 5.20% 2025 rate also specified.
https://www.nebraskalegislature.gov/laws/statutes.php?statute=77-2734.02Utah Legislature - S.B. 60, Income Tax Rate Amendments (2026)
numeric_source / official_valueEnrolled law changes Utah's corporate franchise and income tax from 4.50% to 4.45%, effective for tax years beginning January 1, 2026, under its retrospective-operation clause.
https://le.utah.gov/~2026/bills/sbillenr/SB0060.pdfRSM US - 2026 State Corporate Tax Law Changes, Q2
validation_source / effective-year checkDocuments Georgia H.B. 463 signed May 11, 2026 and the 5.19%-to-4.99% rate change effective for 2026, supporting the year assignment of the official state rate.
https://www.rsmus.com/insights/tax-alerts/2026/state-corporate-income-tax-law-changes-for-the-second-quarterNew Jersey Division of Taxation - Corporate Transit Fee
validation_sourceConfirms the 2.5% additional fee for taxpayers meeting the $10 million taxable-income condition through 2028; not an extra ranked observation.
https://www.nj.gov/treasury/taxation/cbt/corporatetransitfee.shtmlNew York State Department of Taxation and Finance - Corporate Taxes
validation_sourceIndependent January 1, 2026 comparison of top rates for northeastern states, including applicable fees and surcharges.
https://www.tax.ny.gov/data/stats/taxfacts/corporation-tax.htmTennessee Department of Revenue - Franchise and Excise Tax Rates
validation_sourceChecks the 6.50% excise tax on taxable earnings and the distinct net-worth-based franchise tax, which is not included in the ranking rate.
https://www.tn.gov/revenue/taxes/franchise---excise-tax/due-dates-and-tax-rates.html.htmlU.S. Census Bureau - Geography Program Glossary
methodology_sourceDefines the four census regions used for the filter and regional-concentration statistic. No tax rate observations are taken from this source.
https://www.census.gov/programs-surveys/geography/about/glossary.htmlGeorgia Department of Revenue - 2025 IT-611 Corporate Income Tax Instructions
numeric_source / 2025 comparison input onlyThe state's 2025 Form 600 instructions confirm a 5.19% corporate rate effective January 1, 2025 (page 23, estimated corporate tax section). Used for the Georgia 2025-to-2026 percentage-point change, not as a 2026 ranking input.
https://dor.georgia.gov/document/document/2025-it611-corporate-income-tax-instruction-booklet/downloadUtah State Tax Commission - 2024-2025 Annual Report
numeric_source / 2025 comparison input onlyIn Corporate Franchise & Income Tax (printed page 16), the Commission confirms that Utah's corporate rate was reduced from 4.55% to 4.50% for tax years beginning January 1, 2025. The 2026 value comes separately from Utah's S.B. 60.
https://files.tax.utah.gov/tax/commission/reports/fy25report.pdfArkansas General Assembly - 2026 First Extraordinary Session Summary
validation_source / effective-year checkConfirms that the reduction of Arkansas's top corporate income tax from 4.30% to 4.10% applies to tax years beginning January 1, 2027; 4.10% is not a 2026 row value.
https://www.arkleg.state.ar.us/Home/FTPDocument?path=%2Fassembly%2F2025%2F2026F%2FDocuments%2F2026+Fiscal+Session+Summary+Book.pdfTax Foundation - Combined State and Federal Corporate Income Tax Rates, 2026
context_sourceExplains the distinction between the 44 corporate-income-tax states, the no-CIT states and combined federal/state rates. Same organization as the primary dataset; not an additional independent numeric publisher.
https://taxfoundation.org/data/all/federal/combined-state-federal-corporate-income-tax-rates-2026/Related rankings
Closely related StatRanker ranking and data pages selected by topic, entity scope and category. Fewer links are shown when strong matches are limited.